In this article 13 sections
- How to Build Daily Habits for Financial Independence
- 1. Establish a Weekly Money Review Routine
- 2. Create a Practical Budget
- 3. Establish a Steady Saving Routine
- 4. Establish an Emergency Fund
- 5. Practice Thoughtful Spending
- 6. Learn to Manage Debt Carefully
- 7. Invest in Skills That Can Improve Your Earning Potential
- 8. Set Clear Financial Goals
- 9. Make Financial Decisions Based on Information
- 10. Review and Adjust Your Financial Plan
- Frequently Asked Questions
- Conclusion
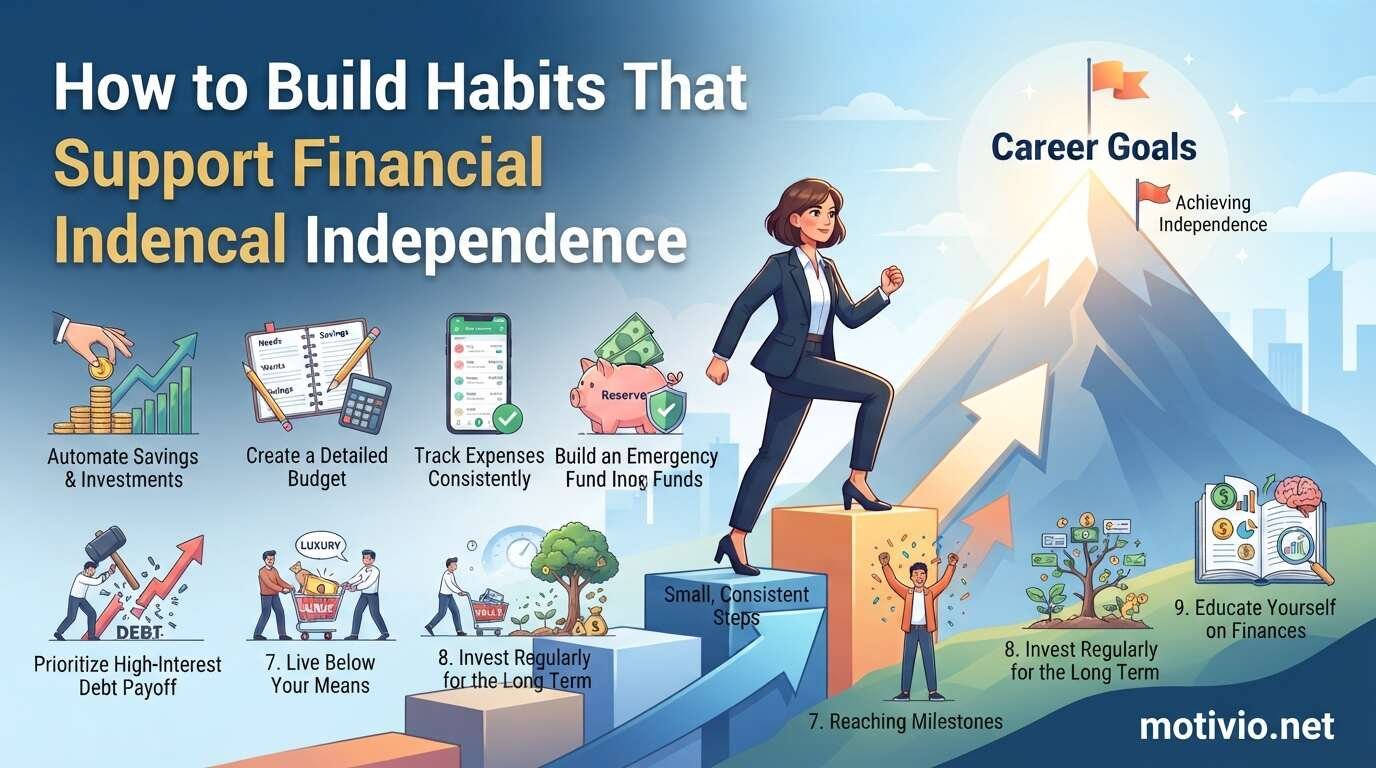
How to Build Daily Habits for Financial Independence
Achieving financial independence is a common aspiration for many individuals. It signifies having sufficient savings, financial assets, and the latitude to make important life choices without feeling entirely reliant on each paycheck.
For some, financial autonomy entails eliminating debt and establishing a safety net. For others, it encompasses saving for retirement, creating additional income streams, or acquiring the freedom to pivot careers.
While income plays a crucial role, financial advancement also hinges on how individuals handle the funds they receive. Daily habits shape spending, saving, planning, and the capacity to manage unforeseen expenses.
The Consumer Financial Protection Bureau clarifies that financial practices consist of the regular behaviors and benchmarks individuals apply to navigate daily financial choices. These patterns can significantly impact how people allocate their resources, save, and prepare for future necessities.
What Is the True Meaning of Financial Independence?
Financial independence lacks a singular definition that universally applies.
An individual with minimal expenses and a dependable emergency fund might experience greater financial peace than another who earns more but carries significant debt and lacks savings.
Nonetheless, achieving financial independence is not solely about minimizing expenditures. It also requires fostering financial stability, making educated choices, and generating assets that enable your future aspirations.
You can visualize it in phases:
1. Assessing your existing financial condition.
2. Overseeing regular expenditures and necessary bills.
3. Creating a financial safety net for unforeseen expenses.
4. Working to lower costly debt when feasible.
5. Saving and investing aligned with your personal situation.
6. Cultivating long-term financial adaptability.
Your initial position could vary from that of others. Emphasize improvements that correspond with your income, obligations, and regional financial context.
1. Establish a Weekly Money Review Routine
One of the most beneficial financial practices is to routinely monitor your expenditures.
Without a transparent view of your earnings and spending, it becomes challenging to detect unnecessary outflows or prepare for future financial requirements.
Dedicate 15 to 20 minutes each week to examine your financial situation.
During this time, assess:
• The total amount of income received.
• The bills and critical expenses settled.
• The amount spent on non-essential items.
• The total savings accumulated.
• Any forthcoming payments that require attention.
You can utilize a notebook, a spreadsheet, or a budgeting software.
The goal is not to criticize every single purchase. It is to gain insights into your financial habits and to make well-informed choices.
2. Create a Practical Budget
A budget serves as a strategy for distributing your income across various needs and objectives.
It aids in comprehending how much money is accessible for essential costs, optional spending, savings, and repayments of debts.
Start by figuring out your regular take-home pay. Then compile a list of your necessary expenses, which encompass housing, food, transport, utilities, and obligatory family duties.
Next, factor in debt repayments, savings, and variable expenditures.
A simple budget might look like this:
| Category | Monthly amount |
| Take-home income | 100% of income |
| Essential expenses | Based on actual costs |
| Debt payments | Required and planned payments |
| Savings | An affordable amount |
| Personal spending | Remaining planned amount |
Avoid replicating the budget allocations of others without taking your specific situation into account. A person who is responsible for a family’s expenses will have drastically different financial habits compared to someone who lives independently. A practical budget should mirror your everyday reality instead of an unattainable standard.
3. Establish a Steady Saving Routine
Setting aside money becomes more manageable when you view it as a regular part of your financial activities instead of just saving what remains at the end. If your earnings permit, allocate a reasonable sum each time you receive income.
For instance, you could save a consistent amount from every paycheck. If your earnings fluctuate month by month, consider saving a percentage of your total income or modifying your savings based on necessary expenditures.
The key is to select a feasible portion that allows you to fulfill your crucial financial responsibilities. If saving is not feasible at this moment, start by analyzing your expenses to determine if any amount can be set aside safely.
Research from the CFPB regarding emergency savings suggests strategies like having a dedicated saving spot and applying behavioral techniques to encourage saving.
4. Establish an Emergency Fund
An emergency fund consists of money set aside for unforeseen costs or financial upheavals.
This can include urgent home repairs, medical expenses, necessary travel, or temporary loss of income. Lacking savings can mean that unexpected costs may necessitate borrowing or postponing necessary payments.
Begin with a reasonable goal that feels attainable, such as saving enough for one minor emergency, and then gradually increase that target. Over time, think about working towards having enough savings to cover several months’ worth of essential expenses if your income and situation permit. Keep emergency funds easily accessible and distinct from the funds you use for daily expenditures.
The right amount varies based on your household expenses, income reliability, available support, and other financial obligations.
5. Practice Thoughtful Spending
Thoughtful spending involves making purchases with intention, rather than allowing impulses to dictate your financial decisions.
Before acquiring something that isn’t necessary, take a moment to reflect and ask yourself:
• Do I really need this item?
• Is it within my budget?
• Am I buying it due to boredom, stress, or external influence?
• Would I rather allocate this money towards another goal?
For larger discretionary purchases, consider postponing your decision for at least 24 hours. This pause allows you to evaluate other options and assess if the purchase is justifiable. Thoughtful spending does not entail eliminating all enjoyable experiences; it signifies allowing space for what you cherish while still upholding crucial financial commitments.
6. Learn to Manage Debt Carefully
Borrowing can hinder financial freedom due to compulsory payments limiting the funds available for other objectives.
Commence by cataloging your debts, noting the remaining amounts owed, interest percentages, minimum payment amounts, and deadlines for payment.
Ensure that you fully comprehend the conditions associated with each debt obligation.
If you have several debts, you can evaluate various repayment strategies. For instance, some individuals focus first on the debt with the highest interest to lower overall interest expenses, while others might opt to tackle a smaller debt initially to foster a feeling of achievement.
Your decision should take into account interest rates, fees, payment demands, and your capacity to cover essential living costs.
Refrain from acquiring additional debt without a full understanding of the total cost of repayment.
If you find it challenging to keep up with payments, think about reaching out to your lender or a qualified financial consultant to explore available options.
7. Invest in Skills That Can Improve Your Earning Potential
While saving money and managing expenses are crucial, your earnings significantly impact the resources available for achieving your financial objectives.
Acquiring valuable skills relevant to your profession might lead to career growth, new job opportunities, or increased income.
Focus on skills that match your interests and the demand in your local job market, such as:
• Written and verbal communication.
• Digital competencies and technical knowledge.
• Managing projects effectively.
• Sales techniques and customer interaction.
• Content development and writing abilities.
• Understanding finance and business practices.
Before committing to a course, verify its curriculum, fee, reputation, and how it aligns with your ambitions.
Having a certificate alone does not guarantee a higher salary. Concentrate on learning applicable skills you can demonstrate.
8. Set Clear Financial Goals
A financial objective becomes easier to tackle when you specify what you aim to accomplish.
Rather than expressing, “I want to be financially secure,” outline a concrete goal.
Examples consist of:
• Accumulating a certain sum for emergencies.
• Reducing a defined debt amount.
• Setting aside funds for education or professional development.
• Establishing savings for a future purchase.
• Increasing contributions toward retirement when possible.
Document the target amount, your planned timeline, and the necessary actions to reach it.
If the goal appears overwhelming, break it down into smaller targets.
For instance, a savings goal can be segmented into monthly or weekly deposits that fit your earnings.
Reassess your objectives when your situation changes.
9. Make Financial Decisions Based on Information
Financial offerings can vary widely in costs, hazards, eligibility criteria, and conditions.
Cultivate a practice of researching prior to making significant decisions.
This should encompass comparing:
• Fees and terms of bank accounts.
• Interest rates on loans and conditions for repayment.
• Coverage and exceptions in insurance policies.
• Investment hazards and associated fees.
• Costs related to training and anticipated advantages.
Utilize trustworthy sources and carefully examine the terms. Be wary of anyone asserting guaranteed high returns or pressuring you into immediate investments.
The CFPB emphasizes the necessity of financial literacy, decision-making capabilities, and diligent research when making financial choices.
For intricate financial matters, consider obtaining guidance from a certified professional who is familiar with your specific situation and location.
10. Review and Adjust Your Financial Plan
Your financial circumstances may evolve due to changes in income, family obligations, housing expenses, educational costs, or unforeseen events.
A budget that was effective six months prior may no longer suit your current situation.
Plan a monthly check-in to address the following:
1. Did I manage to cover my essential expenses?
2. Was I able to set aside any savings?
3. Did I accumulate new debts?
4. What unanticipated expenses arose?
5. What modifications should I implement next month?
If you find yourself lagging, modify your plan instead of giving up on it.
Financial habits should assist you in adapting to reality, rather than inducing feelings of guilt during challenging times.
A Simple Monthly Financial Independence Routine
Your monthly financial checklist
0 of 7 completed
Reset
Examine income and vital expenses
Verify debt amounts and due dates
Establish a practical savings goal
Analyze unnecessary or impulsive spending
Select one skill or professional development activity
Assess progress toward a financial objective
Revise the budget for the upcoming month
Common Financial Habits That Can Hold You Back
Spending without tracking
If you don’t assess your expenditures, minor purchases might gradually deplete funds allocated for important objectives.
Setting unrealistic savings targets
A savings strategy that overlooks vital expenses may prove challenging to maintain. Opt for an amount that aligns with your actual budget.
Comparing your financial life with others
Different individuals may have varying incomes, expenses, familial support, and financial responsibilities. Gauge your progress against your own goals.
Ignoring financial paperwork
Overlooked deadlines, misinterpreted fees, and neglected renewals can lead to unnecessary expenses. Establish reminders and maintain organized records of important documents.
Expecting instant results
Financial advancement typically requires time. Concentrate on sustainable habits rather than seeking immediate solutions.
Frequently Asked Questions
What habits help achieve financial independence?
Establishing a budget regularly, saving consistently, spending consciously, managing debts, enhancing skills, and conducting financial check-ups periodically can all contribute to achieving long-term financial aspirations.
Can I work toward financial independence on a low income?
Absolutely, you can start by gaining insights into your financial situation, cutting unnecessary expenses whenever feasible, overseeing financial responsibilities, and acquiring abilities that could enhance prospective job opportunities. Advancements might be gradual if necessary costs take up the majority of your earnings.
How much should I save each month?
There is no universal figure suitable for everyone. Take into account your earnings, vital expenses, debts, emergency requirements, and financial ambitions. Initiate with a manageable sum and modify it as your situation evolves.
Does financial independence mean being rich?
Not necessarily. For various individuals, it signifies having adequate resources to satisfy basic needs and having the freedom to make more flexible choices. The definition varies based on personal objectives and situations.
Conclusion
Achieving financial independence is not the result of one significant decision. It is cultivated through a succession of financial decisions made over time.
By assessing your finances, budgeting realistically, saving on a regular basis, spending wisely, and enhancing your financial literacy, you can create a more robust base for your future.